I describe my searchGet started

Buying property in Edinburgh with a dedicated expert

Drapeau du Royaume-Uni avec des bandes rouges, blanches et bleues en forme de croix et de diagonales.
An English-speaking Home Finder who lives there
Detective emoji with a hat and magnifying glass.
Spots the good places as soon as they are listed
Gold medal with a red ribbon.
Fights for your offer, not the seller's
Green dollar sign.
The real local price, not the foreigner tax

Why work with a home finder?

Time spent by the buyer
Information symbol.
When you search alone, about 85% of the time is spent on research, and 15% on visits. With a home finder, you only do the visits
Icône de fermeture (croix)
A local network
Purchase price
Virtual pre-visits
Secure formalities
Information symbol.
Customer satisfaction
Only 20% of satisfied buyers according to the 2018 Crédit Foncier study. For its part, Remoters gets a score of 4/5 or 5/5 in 95% of cases
Icône de fermeture (croix)

Buying alone abroad

140 hours
Red cross icon.
Very difficult negotiation
Red cross icon.
Red cross icon.
20%

Buying  with Remoters

20:00
14% discount obtained on average
95%
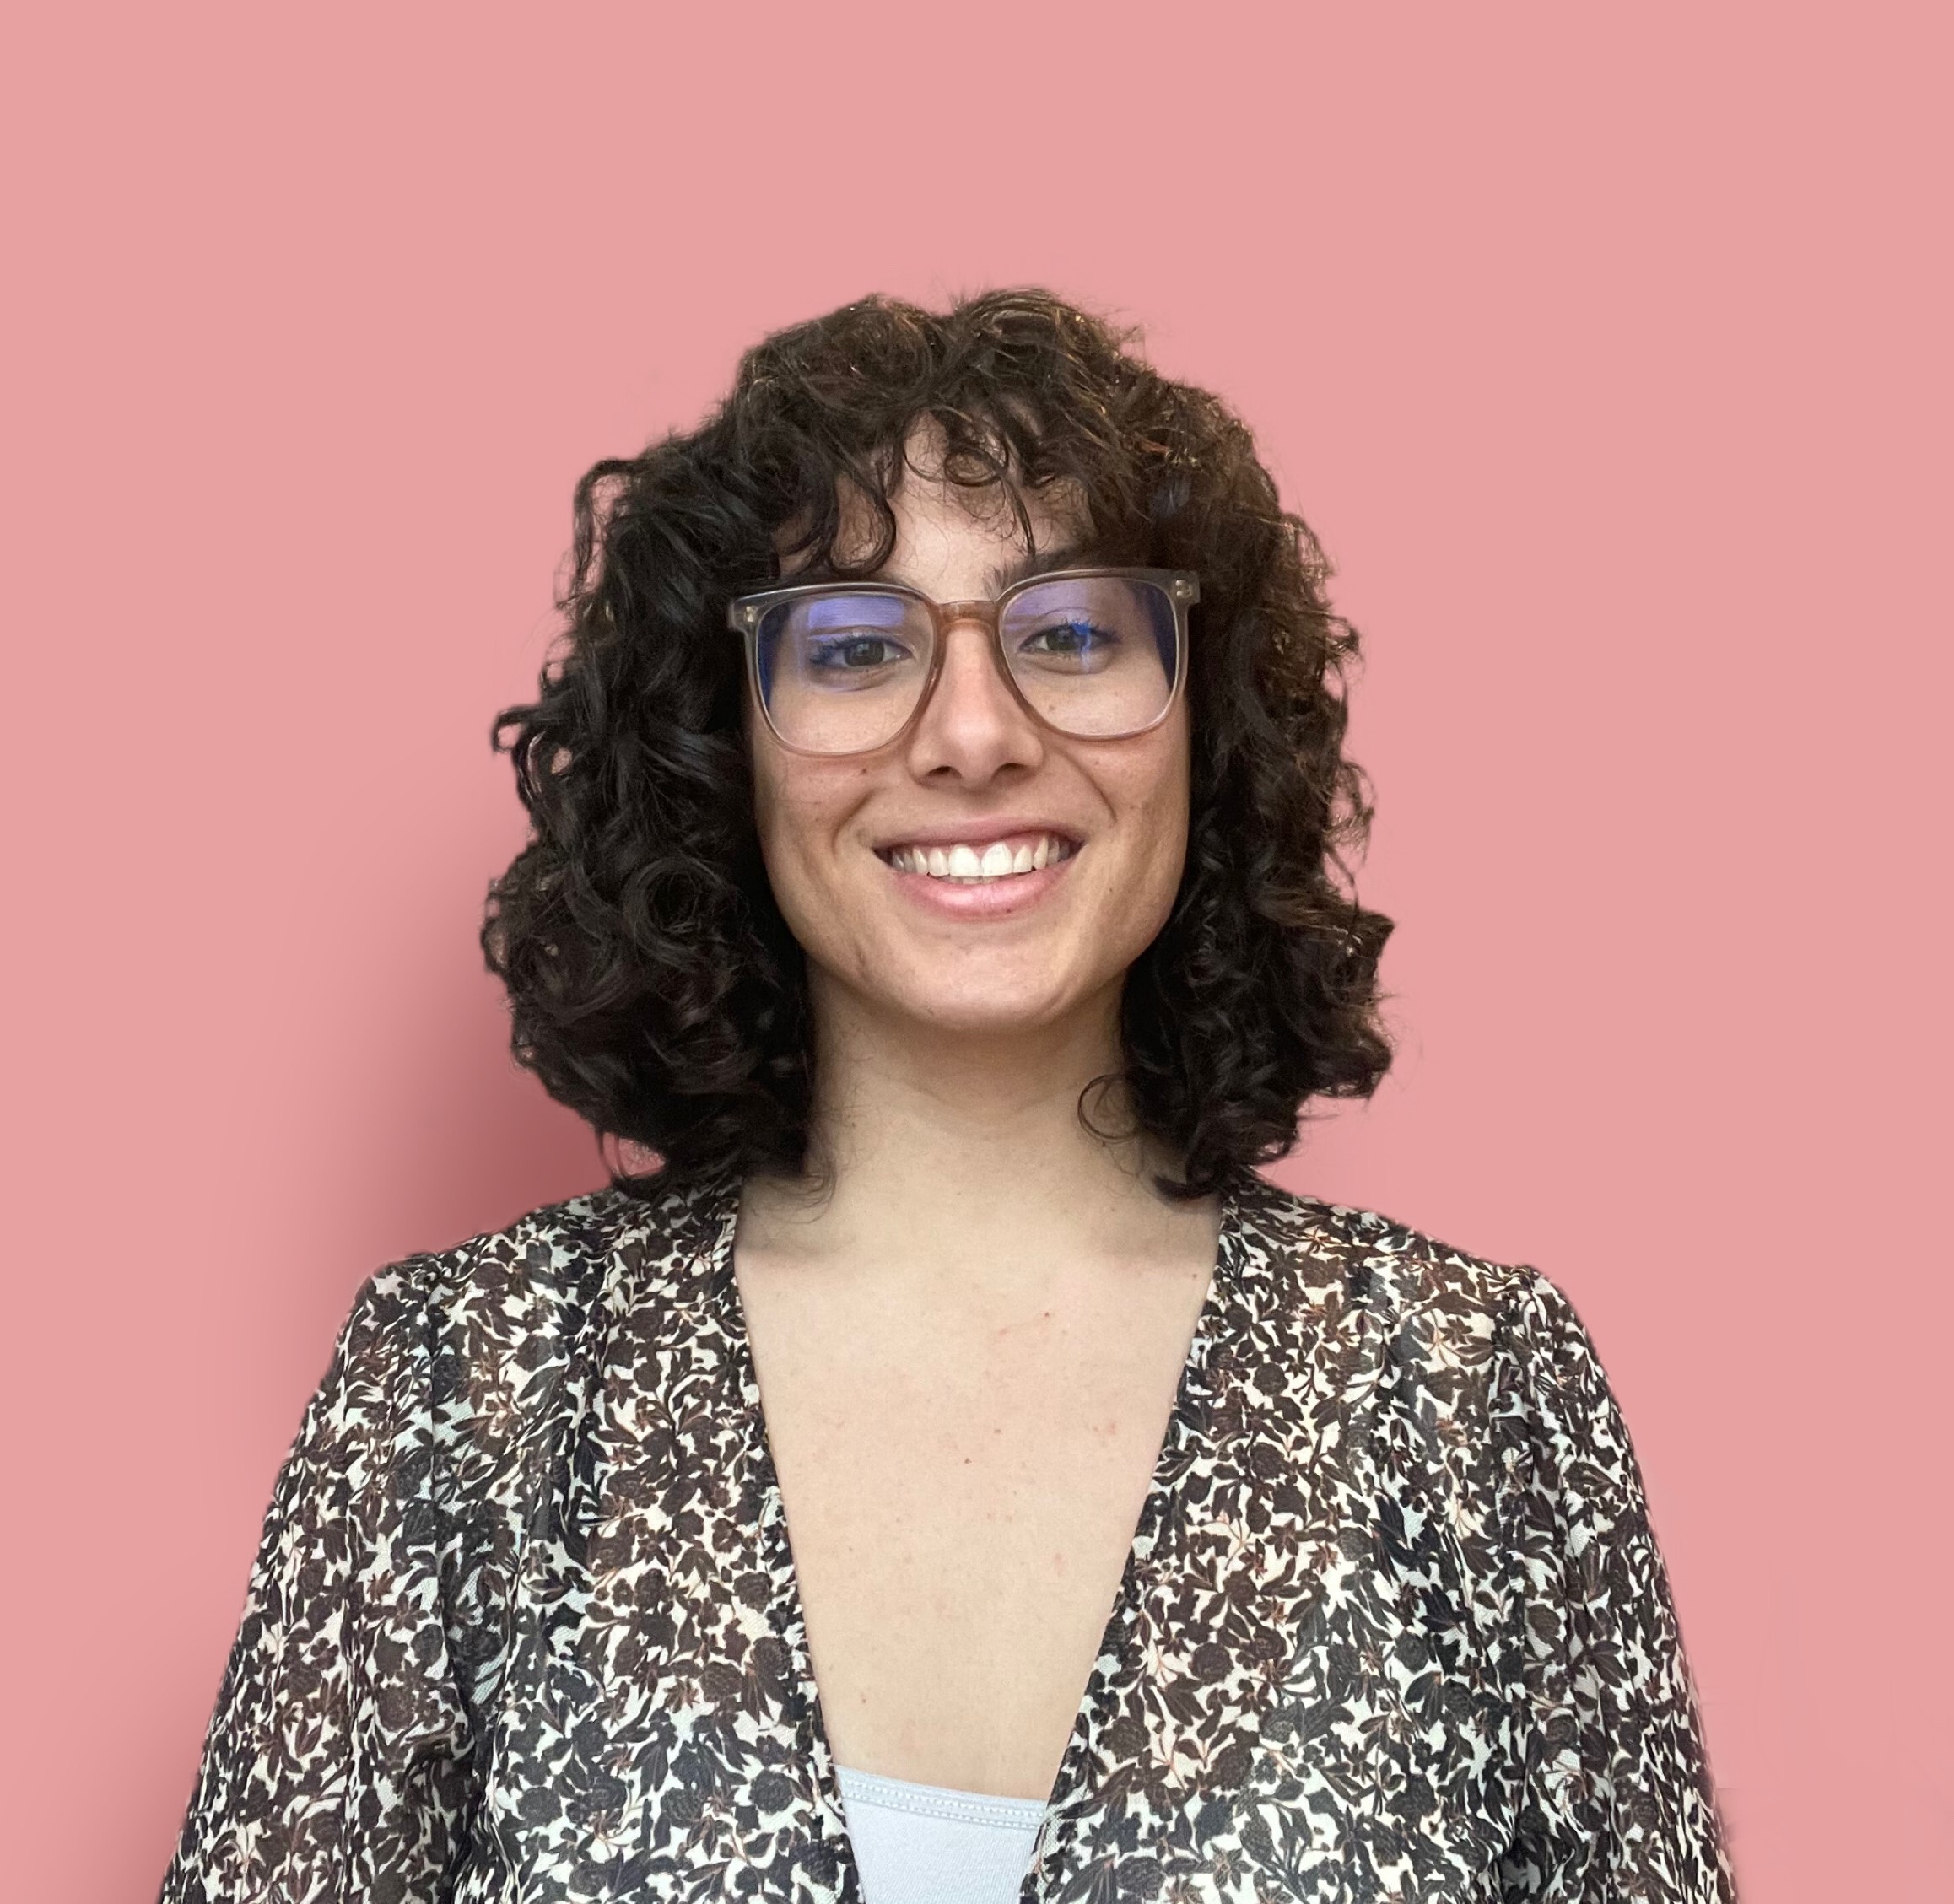
Photo of Aude, home finder in Edimbourg

Aude, or another expert property hunter based in Edinburgh, will personally manage your search.

Local property purchase guide

Acheter un bien immobilier

Buying property in Edinburgh in under 30 seconds: Scotland operates its own distinct legal system. You appoint a solicitor first, then search for a property and review the seller-provided Home Report. When interested, your solicitor lodges a Note of Interest. If competition is high, a Closing Date is set and you submit a sealed best-and-final offer — typically above the Home Report valuation (102.4% on average in Q2 2025, ESPC). Once accepted, solicitors exchange formal letters called missives until the contract is legally binding. Your solicitor conducts title and local authority searches, then transfers funds on the agreed date of entry. Title is registered at the Land Register of Scotland and LBTT (Scotland's purchase tax) is paid. Budget for LBTT, solicitor fees (£800–£1,500 GBP), survey costs, and — for second properties — an Additional Dwelling Supplement of 8% of the purchase price. Average city centre prices stand at around £336,840 GBP (ESPC, Q2 2025). There are no restrictions on foreign buyers purchasing in Edinburgh.

Prices by property type

Price ranges by size, property type and intended use.

Purchase prices in Edinburgh vary considerably by property type. The following figures are drawn from ESPC and market data for 2024–2025:

  • One-bedroom flats: Entry-level one-bedroom flats in outer areas (Leith, Restalrig, Bonnington) typically sell from £150,000–£220,000 GBP (Investropa, 2026). In Leith Walk and Easter Road, the average reached £203,693 GBP in early 2025, up 18.9% year-on-year (Investropa, 2025). Central one-bedroom flats command significantly higher prices.
  • Two-bedroom flats: The most actively traded property type in Edinburgh. In the wider ESPC region, two-bedroom flats in some outer areas sold from around £138,111 GBP on average (ESPC, Q2 2025). In Stockbridge and Canonmills, two-bedroom flats averaged £363,147 GBP in early 2025 (Investropa, 2025).
  • Three-bedroom houses and larger flats: Prices vary widely by location. Family homes in south and southwest Edinburgh typically range from £350,000 to £600,000+ GBP. The southwest Edinburgh average reached £398,563 GBP in Q2–Q3 2025 (ESPC, 2025).
  • Detached houses: Premium detached properties in Murrayfield, Ravelston, and The Grange can exceed £700,000 GBP. The Murrayfield and Ravelston average sold price stands at £732,515 GBP (Macgregor Research, 2024–2025).
  • City-wide average: The overall average selling price across Edinburgh, the Lothians, Fife and the Borders was £298,933 GBP in Q3 2025, up 4.3% year-on-year (ESPC, October 2025). The Edinburgh city centre average was £336,840 GBP in Q2 2025 (ESPC, 2025).

Prices and neighborhood profiles

Areas to compare by budget, lifestyle and purchase project.

Edinburgh's property purchase market is highly segmented by neighbourhood, with significant price variation across the city.

  • City Centre (New Town, Old Town, West End, Stockbridge): The most prestigious and expensive area. Average selling prices reached £341,289 GBP in Q1–Q2 2025, up 8.4% year-on-year (ESPC, 2025). The EH3 postcode recorded 53 million-pound-plus transactions in 2024 alone. Georgian and Victorian architecture, UNESCO World Heritage status, and proximity to financial and cultural institutions drive sustained demand. Two-bedroom flats in Stockbridge averaged £363,147 GBP in early 2025, a 21.7% year-on-year increase (Investropa, 2025).
  • East Edinburgh (Leith, Portobello, Meadowbank, Easter Road): A regenerating area with strong price momentum. Average house prices reached £272,518 GBP in Q2 2025, up 6.5% year-on-year (ESPC, 2025). One-bedroom flats in Leith Walk, Easter Road, Pilrig and Bonnington averaged £203,693 GBP, up 18.9% year-on-year (Investropa, 2025). Leith's waterfront regeneration continues to attract buyers.
  • South Edinburgh (Morningside, Marchmont, Bruntsfield, The Grange): Highly desirable residential neighbourhoods popular with families and professionals. Morningside recorded the highest three-year price growth of any Edinburgh area (Macgregor Research, 2024–2025). Premium Victorian tenements and detached villas command significant premiums.
  • Southwest Edinburgh (Balerno, Currie, Juniper Green): The most expensive area by average price in Q2–Q3 2025, with average prices reaching £398,563 GBP, up 14.8% year-on-year (ESPC, 2025). Larger family homes and green surroundings attract buyers seeking space.
  • West Edinburgh (Murrayfield, Ravelston, Corstorphine): Murrayfield and Ravelston are Edinburgh's most expensive areas by average sold price at £732,515 GBP (Macgregor Research, 2024–2025). Detached and semi-detached houses dominate.
  • North Edinburgh (Trinity, Newhaven, Granton): More affordable entry points with improving connectivity. Trinity recorded a 10.8% increase in sales volume year-on-year (Macgregor Research, 2024–2025).

Real estate market trends

Price dynamics, demand level and the most sought-after properties.

Edinburgh's residential property purchase market has demonstrated sustained long-term growth, underpinned by strong employment, a major university sector, and constrained central housing supply.

According to ESPC data, the average selling price across Edinburgh, the Lothians, Fife and the Borders reached £298,933 GBP in Q3 2025, representing a 4.3% year-on-year increase (ESPC, October 2025). Within Edinburgh city itself, the city centre recorded an average selling price of £336,840 GBP in Q2 2025, up 8.8% year-on-year (ESPC, 2025).

Over a longer horizon, the median Edinburgh house price rose from approximately £190,000 GBP in October 2015 to £270,000 GBP in October 2025 — a nominal increase of around 42% over a decade (Investropa, 2025). Demand has consistently outpaced supply in central and inner-city areas, keeping competition among buyers intense: properties sold at an average of 102.4% of their Home Report valuation in Q2 2025, a 0.3 percentage point increase year-on-year (ESPC, 2025). Sales volumes also rose by 8% year-on-year in Q3 2025.

Looking ahead, national forecasts from Belvoir Estate Agents project a 2%–3% price increase across the UK in 2025, a trend expected to be reflected in Edinburgh. The city's status as Scotland's capital, its UNESCO World Heritage Sites, and its role as a financial and technology hub continue to support structural demand for property purchase.

Total budget and taxes

Purchase price, taxes, fees and additional costs to anticipate.

When purchasing property in Edinburgh, the headline purchase price is only part of the total acquisition budget. Buyers must account for several additional costs that can add 5% to 10% to the overall outlay.

  • Land and Buildings Transaction Tax (LBTT): Scotland's property purchase tax applies to residential transactions above £145,000 GBP. The 2025/26 progressive bands are: 0% up to £145,000 GBP; 2% on £145,001–£250,000 GBP; 5% on £250,001–£325,000 GBP; 10% on £325,001–£750,000 GBP; 12% above £750,000 GBP (Revenue Scotland, 2025). First-time buyers benefit from a raised nil-rate threshold of £175,000 GBP, saving up to £600 GBP.
  • Additional Dwelling Supplement (ADS): Buyers acquiring a second or additional residential property pay an ADS of 8% of the full purchase price, increased from 6% in December 2024 (Revenue Scotland, 2024). On a £250,000 GBP property, this represents £20,000 GBP in ADS alone.
  • Solicitor / conveyancing fees: Typically £800–£1,500 GBP for standard residential purchases, though fees vary with property value and transaction complexity.
  • Survey / Home Report: The seller commissions the Home Report in Scotland; buyers may commission an independent survey for additional assurance, costing approximately £300–£600 GBP depending on property size.
  • Mortgage arrangement and valuation fees: Variable by lender; typically £500–£2,000 GBP in total.
  • Land Register registration fee: Payable to Registers of Scotland; scales with purchase price.
  • Removal and miscellaneous costs: Budget separately for removals, utility connections and any immediate refurbishment.

There are no additional purchase taxes specifically targeting non-resident or foreign buyers in Scotland, unlike some other jurisdictions (Wise, 2024).

Purchase process

How the project unfolds from defining your criteria to receiving the keys.

Buying property in Edinburgh follows the distinct Scottish legal process, which differs materially from the system in England and Wales. The key stages are:

  1. Appoint a solicitor: In Scotland, a solicitor is essential from the outset — many Scottish solicitor firms also act as estate agents. Instruct your solicitor before viewing properties so that they can act swiftly when required.
  2. Obtain a mortgage agreement in principle (AIP): Confirm your borrowing capacity with a lender before making any offer.
  3. Search and view properties: Properties are listed through solicitor estate agents, ESPC (Edinburgh Solicitors Property Centre), and national portals. Attend viewings and review the Home Report — a mandatory survey and valuation document provided by the seller.
  4. Note of Interest: When seriously interested in a property, your solicitor submits a formal Note of Interest to the selling agent. This ensures you are notified of any Closing Date set for offers (MoneyHelper, 2024).
  5. Closing Date and offer: If multiple buyers note interest, the seller's agent fixes a Closing Date by which all parties must submit their best and final written offer simultaneously. In Edinburgh's competitive market, buyers frequently offer above the Home Report valuation — the average achieved in Q2 2025 was 102.4% of valuation (ESPC, 2025). Offers are submitted in formal legal form by your solicitor.
  6. Conclusion of Missives: Once an offer is accepted, solicitors exchange a series of formal letters (missives) to agree all terms of sale. The transaction becomes legally binding only when missives are concluded — a key protection for both parties.
  7. Conveyancing and searches: Your solicitor conducts title searches in the Land Register of Scotland (or General Register of Sasines for older titles), local authority searches, and personal register searches to confirm the seller's legal capacity to sell and identify any encumbrances.
  8. Settlement (completion): On the agreed date of entry, the buyer's solicitor transfers funds to the seller's solicitor. Once funds are received and the seller has vacated, keys are released. The solicitor then registers the title at the Land Register of Scotland and submits the LBTT return to Revenue Scotland.

Required documents

The documents to prepare when buying and financing property locally.

Scottish solicitors are legally required to carry out Anti-Money Laundering (AML) checks on every property purchase. Buyers should prepare the following documents before instructing a solicitor:

  • Photographic identity: Valid passport or national identity card.
  • Proof of address: Recent utility bill or bank statement (typically dated within three months).
  • Proof of funds / source of wealth: Bank statements, savings account statements, or investment account statements demonstrating the origin of purchase funds. If funds include a gifted deposit, a signed Gifted Deposit Letter from the donor is required, confirming the gift is non-repayable and carries no security over the property.
  • Mortgage agreement in principle (AIP): If financing the purchase, a lender's AIP confirms borrowing capacity and strengthens any offer.
  • Proof of existing property ownership (if applicable): Required when claiming first-time buyer LBTT relief or when ADS liability is being assessed.
  • Solicitor's instruction form: Completed client-care documentation required by the Law Society of Scotland.

For non-resident buyers, additional documentation may be requested to verify overseas income, foreign bank accounts, or corporate ownership structures. Having all documents ready before noting interest in a property significantly accelerates the transaction timeline.

Legal and technical checks

Checks on title, land registry, compliance and the actual condition of the property.

Scottish conveyancing involves a thorough programme of legal and technical due diligence, conducted by the buyer's solicitor before missives are concluded.

Title and ownership checks:

  • Search of the Land Register of Scotland (or General Register of Sasines for older, unregistered titles) to confirm the seller's ownership and identify any standard securities (mortgages), servitudes, real burdens, or other encumbrances affecting the property.
  • Review of the Title Sheet, which sets out all rights and obligations attached to the property, including shared maintenance responsibilities for common areas in tenement buildings.
  • Search of the Register of Inhibitions and Adjudications (personal registers) to verify that the seller has full legal capacity to sell and is not subject to bankruptcy or other legal restrictions that could render the transfer reversible (Raeburn Christie Clark & Wallace).

Local authority and planning searches:

  • Local authority search to identify any planning consents, enforcement notices, road adoption status, or proposed developments affecting the property or its immediate surroundings.
  • Review of building warrants and completion certificates for any alterations or extensions carried out since the property was built.

Home Report review:

  • The seller-commissioned Home Report comprises a Single Survey (structural condition and valuation), an Energy Performance Certificate (EPC), and a Property Questionnaire. The buyer's solicitor reviews this document and advises on any material issues flagged by the surveyor.
  • Buyers may commission an independent additional survey for greater assurance, particularly for older or unusual properties.

Mortgage lender requirements:

  • If purchasing with a mortgage, the lender will instruct its own valuation and may require specific conditions to be satisfied before releasing funds.

Non-resident financing

Deposit, mortgage, supporting documents and constraints specific to foreign buyers.

There are no legal restrictions on non-residents or foreign nationals purchasing property in Edinburgh or anywhere in Scotland (estateagentpower.com, 2024). However, accessing mortgage finance as a non-resident requires careful preparation.

  • Cash purchases: Many overseas buyers purchase in cash, which provides a competitive advantage in Edinburgh's fast-moving market where Closing Dates are common. Cash buyers avoid lender requirements and can move more quickly to conclude missives.
  • Expat and foreign national mortgages: A number of UK lenders and specialist brokers offer mortgage products for non-residents and expatriates secured on Scottish property. Eligibility criteria vary significantly by lender; some require a minimum period of UK residency or Indefinite Leave to Remain. Specialist mortgage brokers with experience in cross-border transactions are strongly recommended.
  • Loan-to-value (LTV) ratios: Non-resident borrowers may face lower maximum LTV ratios than UK-resident buyers, typically requiring a larger deposit.
  • Source of funds verification: All buyers — resident or non-resident — must satisfy AML checks. Non-residents should be prepared to provide comprehensive documentation of overseas income, foreign bank accounts, and the origin of purchase funds.
  • No nationality surcharge: Scotland does not impose an additional purchase tax on non-resident buyers (Wise, 2024).
  • Currency considerations: Buyers purchasing in GBP from a foreign currency account should factor in exchange rate risk and consider forward contracts or currency specialists to manage exposure.

Investment and rental potential

Rental demand, rents, indicative yield and rules to anticipate.

Edinburgh is consistently ranked among the UK's strongest property investment markets, driven by a large student population, a major financial services sector, and year-round tourism demand.

Purchase price context: The average selling price in Edinburgh city centre reached £336,840 GBP in Q2 2025, up 8.8% year-on-year (ESPC, 2025). Entry-level one-bedroom flats in areas such as Leith, Restalrig, and Bonnington can be acquired from approximately £150,000–£220,000 GBP (Investropa, 2026).

Gross rental yields vary by location and property type. In Q4 2024, one-bedroom properties in certain Edinburgh areas achieved gross yields of up to 8%, while two- and three-bedroom properties averaged around 6.1% (Landlord Today / ESPC Lettings, 2025).

Key investment considerations for buyers:

  • Additional Dwelling Supplement (ADS): Buyers acquiring a second or investment property pay ADS at 8% of the full purchase price (increased from 6% in December 2024), which materially affects initial yield calculations and must be factored into acquisition costs.
  • Capital growth: Edinburgh's median price rose approximately 42% in nominal terms over the decade to 2025 (Investropa, 2025), supporting long-term capital appreciation alongside income returns.
  • Hotspot areas: Leith and the waterfront regeneration zone, the EH3 postcode (New Town, West End, Stockbridge), and the southwest of the city have all recorded strong price growth in 2024–2025.
  • Regulatory environment: Scotland has an active legislative framework governing the private rented sector; buyers intending to let a purchased property should seek specialist legal and tax advice before completing.

Negotiation method

Fair-price analysis and arguments used to defend the purchase offer.

Negotiating a property purchase in Edinburgh requires understanding the Scottish sealed-bid system, which differs fundamentally from the open negotiation model common in many other countries.

The Closing Date process: When a property attracts significant interest, the seller's agent fixes a Closing Date — a deadline by which all interested buyers must submit their best and final written offer simultaneously. Offers are sealed; no buyer knows what others have bid. The seller then selects the most attractive offer, which is usually (but not always) the highest price (Cameron Stephen and Co, 2024).

Pricing conventions:

  • Properties are typically marketed as Offers Over a stated price (often the Home Report valuation), Fixed Price, or Offers Around.
  • In Edinburgh's competitive market, buyers regularly offer above the Home Report valuation. The city-wide average in Q2 2025 was 102.4% of Home Report value (ESPC, 2025), with central and sought-after areas commanding higher premiums.

Practical negotiation tips for buyers:

  • Instruct a solicitor before viewing so that a Note of Interest can be lodged immediately.
  • Study recent comparable sales in the same street or building to calibrate your offer.
  • A mortgage AIP or proof of cash funds strengthens your position.
  • Consider non-price terms: a flexible date of entry aligned with the seller's needs can differentiate your offer at a Closing Date.
  • On properties with less competition (e.g., those that have been on the market for several weeks), direct negotiation below the asking price may be possible.

Fees and service scope

Remuneration model, included services and possible additional costs.

In Edinburgh, the buying process is managed almost exclusively by solicitors, many of whom also operate as estate agents — a distinctive feature of the Scottish property market. Understanding the fee structure on both sides of the transaction is essential for accurate budgeting.

Buyer's solicitor fees typically cover:

  • Legal advice and client onboarding (AML checks, ID verification)
  • Reviewing the Home Report and advising on its findings
  • Submitting the Note of Interest and preparing the formal offer
  • Negotiating and concluding missives
  • Conducting title, local authority, and personal register searches
  • Managing the transfer of funds at settlement
  • Registering the title at the Land Register of Scotland
  • Submitting the LBTT return to Revenue Scotland

Conveyancing fees for buyers in Edinburgh typically range from £800 to £1,500 GBP for standard residential transactions, though fees increase with property value and complexity (SolicitorMag, 2025). Many firms offer fixed-fee quotes; always request a full written breakdown including disbursements (search fees, registration dues) before instructing.

Seller's estate agent / solicitor fees for marketing and sale are paid by the seller and do not form part of the buyer's cost. In Scotland, the seller is also responsible for commissioning and paying for the Home Report before the property is listed.

Prepare your property purchase

Describe your project, budget and criteria. A local home finder can search for properties, organize viewings, verify information and support you during the negotiation.

Describe my project

How does it work?

1

Your home finder researches the ideal property based on your criteria.

2
They conduct property viewings, some on your behalf, others with you in person or remotely.
3
They negotiate the price and terms on your behalf. The home finder is still at 100% on the buyer's side.
4
They assist you until all documents are signed
5
It accompanies you until the signature of all documents, to avoid pitfalls.
A couple lying on a bed, embracing.

Our home finders around the world!

Remoters continues to grow!
We are recruiting new home finders, do not hesitate to apply.
World map with red markers in the Americas, Europe, Africa and Asia.I am applying

FAQ

A hand pointing at a laptop screen while the other types.

Why choose an English-speaking home finder in Edinburgh?

Searching for a property abroad requires time, organization, and a good understanding of local regulations, which may differ from those in France (notaries, land registry, taxation, etc.). A home finder helps simplify the process by managing the search, selecting relevant properties, organizing viewings, and reviewing legal documents.

They work closely with the buyer to define clear criteria, identify suitable opportunities, and negotiate the best possible price. They may attend property visits on the buyer’s behalf or accompany them during a stay in Istanbul.

Thanks to their local network, the home finder also facilitates the legal and logistical steps of the purchase. From the initial search to the final signature, they provide tailored support and help ensure a smooth and secure buying experience.

‍

A person in a checked shirt using a blue calculator on a wooden desk.
How much does the Remoters home finder service cost?

Remoters works with home finders around the world. Since real estate prices vary greatly depending on the location, it is difficult to apply a single pricing structure.

Each home finder sets their own fees based on the complexity of the project and the local market. You can contact them directly to learn more about their terms and evaluate the value they can bring to your purchase.

In many cases, the home finder’s fee is largely offset by negotiating a better purchase price and helping reduce legal and administrative risks.

‍

Hand holding keys with a house-shaped keychain near a door lock.
Will I have access to all the offers on the market?

There are three main types of property listings on the real estate market:

  • Agency listings
  • Private listings (from individual sellers)
  • Fast-moving listings, meaning properties that sell within days

When searching on your own, you will usually access the first two categories, provided you are familiar with the main listing platforms and able to identify outdated or misleading ads sometimes used to attract buyers. The third category often goes before you can react.

Home finders can provide access to all three types of opportunities. They screen listings before presenting them and use their network to react quickly when a relevant property comes up.

The best opportunities go fast. Being ready to make an offer as soon as a property is listed allows buyers to position themselves early. Thanks to their professional network, a home finder can help you act on these opportunities in time.

‍

Modern kitchen with a double sink, chrome tap, gas stove, green decorations and yellow lemons.
Home finder vs real estate agent

When searching for a property abroad, your need is typically a home finder🕵️

A real estate agent represents the seller through a sales mandate and aims to market properties to potential buyers.

A home finder, on the other hand, represents the buyer through a search mandate. They do not have properties to sell. Instead, they search for a specific property based on the buyer’s criteria, sourcing opportunities from both private sellers and agencies.

While the real estate agent advises and supports the seller throughout the transaction, the home finder advises and assists the buyer at every step of the purchasing process, always acting in the buyer’s best interest.

‍

A man in a suit holding a small colourful house in his hand in front of a calculator.
How do you choose the right home finder?

The right home finder is the one who helps you purchase a property that best matches your needs and criteria, at an optimized price.

Their fees should remain reasonable and create real value for your project. In many cases, the cost of the service is largely offset by stronger negotiation outcomes and better purchase conditions 🤑

When buying abroad, working with an English-speaking home finder who is well established in the local market can be particularly beneficial. This helps reduce misunderstandings and increases your chances of accessing high-quality opportunities through their local network.

Two men's hands clasped in a handshake against a neutral beige background.

Interested in becoming a home finder for Remoters in Edinburgh ?

You should have:

🧙 Strong experience in the local real estate market
🌐 A solid network to access a wide range of property opportunities
⚖️ In-depth knowledge of local regulations
💸 Excellent negotiation skills
🛎️ Above all, a genuine desire to support clients in their property purchase projects

If this sounds like you, we encourage you to apply — we would be happy to welcome you to our network.

Button TextButton Text