I describe my searchGet started

Buying property in Dubai with a dedicated expert

Drapeau du Royaume-Uni avec des bandes rouges, blanches et bleues en forme de croix et de diagonales.
An English-speaking Home Finder who lives there
Detective emoji with a hat and magnifying glass.
Spots the good places as soon as they are listed
Gold medal with a red ribbon.
Fights for your offer, not the seller's
Green dollar sign.
The real local price, not the foreigner tax

Why work with a home finder?

Time spent by the buyer
Information symbol.
When you search alone, about 85% of the time is spent on research, and 15% on visits. With a home finder, you only do the visits
Icône de fermeture (croix)
A local network
Purchase price
Virtual pre-visits
Secure formalities
Information symbol.
Customer satisfaction
Only 20% of satisfied buyers according to the 2018 Crédit Foncier study. For its part, Remoters gets a score of 4/5 or 5/5 in 95% of cases
Icône de fermeture (croix)

Buying alone abroad

140 hours
Red cross icon.
Very difficult negotiation
Red cross icon.
Red cross icon.
20%

Buying  with Remoters

20:00
14% discount obtained on average
95%
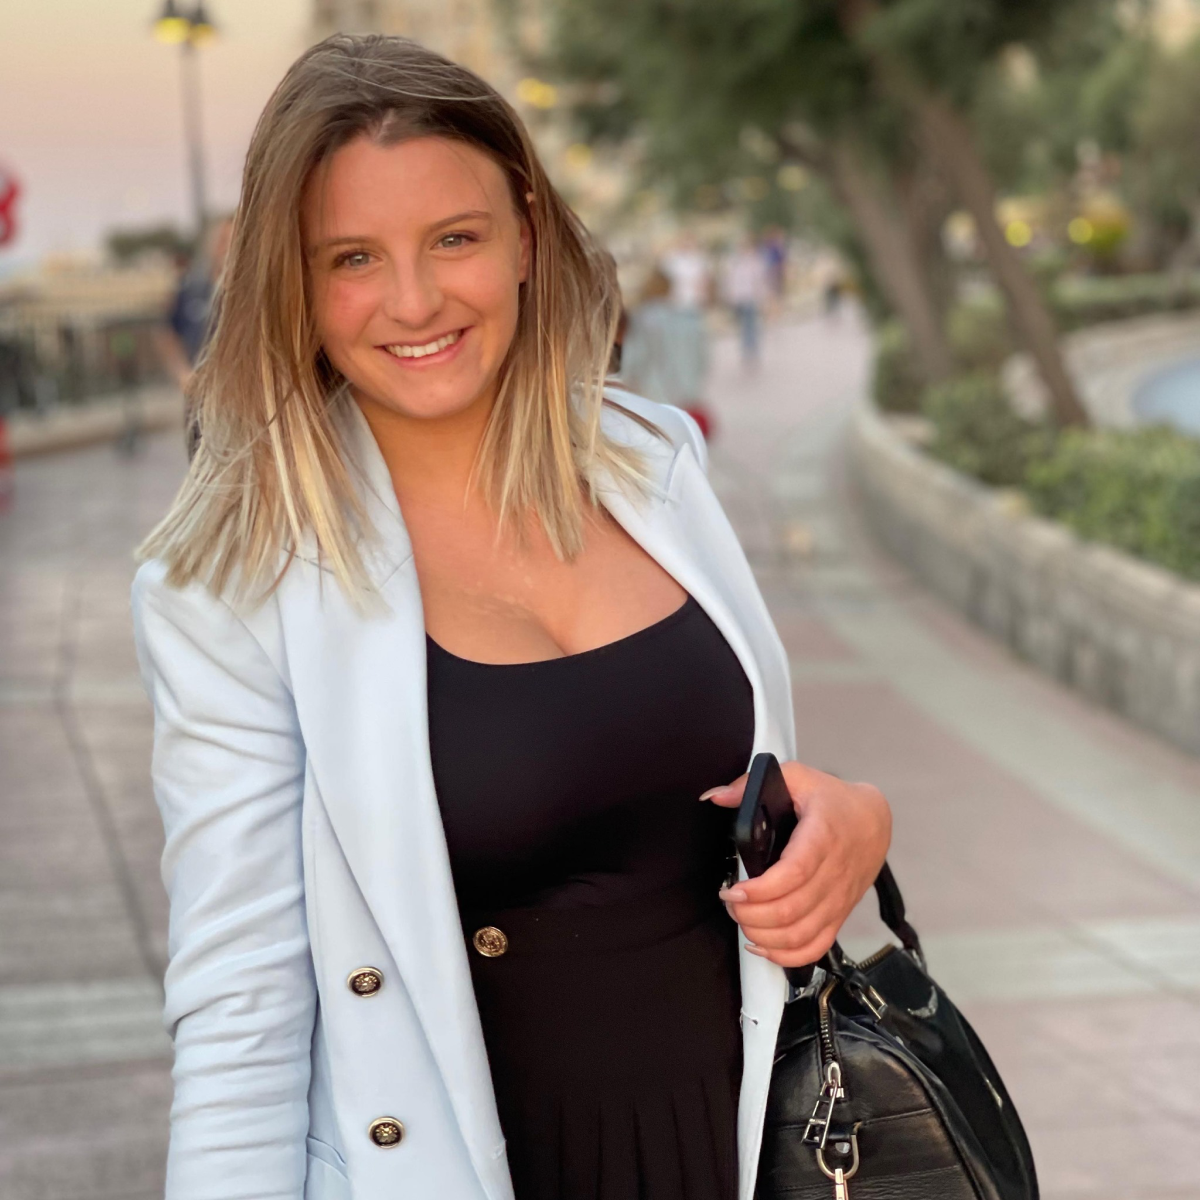
Photo of Aude, home finder in Dubai

Aude, or another expert property hunter based in Dubai, will personally manage your search.

Local property purchase guide

Acheter un bien immobilier

Buying property in Dubai in 30 seconds:

Foreign nationals can purchase property with full freehold ownership rights in Dubai's designated freehold zones — no local partner required. The purchase process is straightforward and fully regulated by the Dubai Land Department (DLD) and RERA.

The key steps are: search → offer → sign Form F (MOU) → obtain NOC → transfer at DLD Trustee Office → receive Title Deed.

Budget 7–10% above the purchase price for transaction costs, of which the largest item is the 4% DLD transfer fee. Agency commission is typically 2% + VAT. Non-resident buyers can access mortgage financing with a down payment of 25–50% depending on the property type and lender.

The market has seen strong price growth: average sales prices rose 20% in 2024 to AED 1,597/sqft (Deloitte, February 2025), and transaction volumes reached a record 214,912 sales in 2025 (DLD data). Gross rental yields average approximately 6.9% across the city, with studios and smaller apartments generating the highest returns. Purchasing a property valued at AED 2,000,000 or more may qualify the buyer for a UAE Golden Visa.

Prices by property type

Price ranges by size, property type and intended use.

The following purchase price ranges are indicative of the Dubai residential sales market. All figures are in AED and sourced from Property Finder and Bayut market data (2024–2025).

  • Studio apartment: Average purchase price approximately AED 790,000. Typical size: 400–500 sq ft. Gross rental yield: approximately 7.4% (source: Property Finder).
  • 1-bedroom apartment: Average purchase price approximately AED 1,500,000. Typical size: 700–800 sq ft. Gross rental yield: approximately 6.3% (source: Property Finder).
  • 2-bedroom apartment: Average purchase price approximately AED 2,700,000. Typical size: 1,050–1,250 sq ft. Gross rental yield: approximately 5.4% (source: Property Finder).
  • 3-bedroom apartment: Average purchase price approximately AED 5,600,000. Typical size: 1,800–2,000 sq ft. Gross rental yield: approximately 4.9% (source: Property Finder).
  • 3-bedroom villa / townhouse: Purchase prices typically range from AED 2,500,000 to AED 4,000,000 in affordable communities such as The Springs or Mudon. More established communities command higher prices (source: market data, 2024).
  • Villa (all sizes, market average): The average sale price for villas in Dubai stands at approximately AED 6,747,229 (source: Bayut, 2025). Entry-level townhouses in communities such as Town Square average approximately AED 2,830,000.
  • Luxury and ultra-luxury: Properties in Palm Jumeirah, Emirates Hills, and prime waterfront developments can exceed AED 20,000/sqm, with ultra-luxury units reaching significantly higher levels.

The overall average selling price for apartments in Dubai is approximately AED 2,000,000 (source: Property Finder). Prices vary significantly by location, floor level, view, finishing quality, and proximity to amenities.

Prices and neighborhood profiles

Areas to compare by budget, lifestyle and purchase project.

Dubai's property purchase market is divided into designated freehold zones where foreign nationals can buy property with full ownership rights. Each area has a distinct profile, price range, and buyer demographic.

  • Downtown Dubai: Emaar's flagship district surrounding the Burj Khalifa. Predominantly high-rise apartments. Purchase prices range from approximately AED 2,200 to AED 4,500/sqft. The area recorded around 3,400 transactions in 2024. Gross yields average 4.5–6.5%. Service charges are among the highest in the city (AED 20–35/sqft). Suited to buyers seeking a prime address and strong short-term rental potential (source: Oliva, 2024).
  • Dubai Marina: A 3.5 km man-made canal lined with over 200 residential towers. Purchase prices range from AED 1,500 to AED 2,800/sqft. Gross yields average 5.5–7.5%. Proximity to JBR beach and tram connectivity drive consistent demand (source: Oliva, 2024).
  • Business Bay: A mixed-use district flanking the Dubai Canal, adjacent to Downtown. Prices average AED 1,400 to AED 2,200/sqft. Over 5,200 transactions were recorded in 2024, making it one of Dubai's most liquid markets. Gross yields range 6.5–8.5% (source: Oliva, 2024).
  • Jumeirah Lakes Towers (JLT): A DMCC free zone community of 80 towers around three artificial lakes. Prices range from AED 900 to AED 1,400/sqft. One-bedroom apartments start from approximately AED 700,000. Gross yields run 6.5–8% (source: Oliva, 2024).
  • Jumeirah Village Circle (JVC): One of Dubai's most affordable freehold communities, popular with first-time buyers and investors. Consistently ranks among the highest-yielding areas in the city. Suited to budget-conscious buyers seeking strong income returns.
  • Dubai Hills Estate: Emaar's 2,700-acre master community with apartments, townhouses, and villas. Prices range from AED 1,400 to AED 2,500/sqft. Villas have appreciated 40–55% since launch. Gross yields run 5–7%. A planned metro extension (expected 2028) is anticipated to add further value (source: Oliva, 2024).
  • Palm Jumeirah: Dubai's iconic man-made island. The most prestigious address in the city. Villa purchase prices average AED 6,159/sqft (source: MyBayut, 2025). Properties in Palm Jumeirah can reach AED 32,000/sqm for ultra-luxury units. Suited to high-net-worth buyers seeking a trophy asset.
  • Arabian Ranches: A family-oriented villa community by Emaar. Average villa purchase price of approximately AED 2,241/sqft (source: MyBayut, 2025). Popular with families seeking a suburban lifestyle with access to schools and golf.

Real estate market trends

Price dynamics, demand level and the most sought-after properties.

Dubai's residential sales market has experienced sustained and significant growth over the past decade, underpinned by population growth, infrastructure investment, and strong international demand.

  • Long-term price growth: Average purchase prices per square foot rose from AED 1,003/sqft in 2014 to AED 1,524/sqft in 2024, representing a cumulative increase of 51.9% over ten years (source: Dubai property market data, 2024).
  • 2024 price acceleration: According to Deloitte's Dubai Real Estate Predictions report (February 2025), average residential sales prices rose by 20% in 2024, reaching AED 1,597/sqft on average. Villas outperformed apartments in price growth, reflecting a sustained shift in lifestyle preferences.
  • Record transaction volumes: The DLD recorded 180,860 residential sales transactions in 2024. In 2025, this figure rose further to 214,912 sales worth AED 682.5 billion AED, an 18.8% increase in volume year-on-year (source: DLD data via Real Estate Club Dubai, updated April 2026).
  • Off-plan vs. ready market: Off-plan sales have grown significantly as a share of total transactions, driven by developer payment plan structures and new master community launches. The secondary (ready) market remains active, particularly in established communities.
  • Demand drivers: Population growth (Dubai's population increased approximately 5% in 2024 according to Deloitte), continued expatriate inflows, and government initiatives including residency visa reforms linked to property investment have sustained buyer demand.
  • 2025 outlook: Deloitte's 2025 report notes that an influx of new supply later in 2025 may moderate the pace of price increases, though overall market momentum is expected to remain positive.

Total budget and taxes

Purchase price, taxes, fees and additional costs to anticipate.

When purchasing property in Dubai, the headline purchase price is only part of the total acquisition cost. Buyers should budget an additional 7–10% above the purchase price to cover all mandatory transaction-related expenses (source: Property Finder, 2026).

  • DLD Transfer Fee: 4% of the purchase price, payable to the Dubai Land Department (DLD). In practice, the buyer typically bears the full 4%, unless otherwise negotiated with the seller.
  • Title Deed Issuance Fee: A fixed administrative fee payable to the DLD upon registration of ownership.
  • DLD Registration Fee: A fixed fee based on property value, collected at the trustee office at the time of transfer.
  • Real Estate Agency Commission: Approximately 2% of the purchase price for secondary market transactions, subject to 5% VAT (source: Kotook / DLD-registered brokers).
  • Developer NOC (No Objection Certificate): For resale properties, the developer issues an NOC confirming no outstanding dues. Fees typically range from AED 500 to AED 5,000 plus VAT, depending on the developer.
  • Mortgage Registration Fee (if applicable): 0.25% of the loan amount, payable to the DLD, plus a fixed administrative charge.
  • Property Valuation Fee (if financing): Required by the bank before mortgage approval; cost varies by lender.

As an illustrative example, on a purchase of AED 2,000,000, total transaction costs (excluding the purchase price itself) can amount to approximately AED 140,000–200,000 (source: Property Finder, 2026).

Taxation: Dubai levies no personal income tax, no capital gains tax on property sales, and no annual property tax on residential real estate. The only recurring government charge is a service charge (maintenance fee) set by the developer or owners' association, which varies by community and property type.

Purchase process

How the project unfolds from defining your criteria to receiving the keys.
  1. Define Budget and Obtain Mortgage Pre-Approval (if financing): Before beginning your property search, establish your total acquisition budget including transaction costs (7–10% above purchase price). If using bank financing, obtain a mortgage pre-approval letter to confirm your borrowing capacity.
  2. Property Search and Viewings: Search listings on RERA-regulated platforms (Property Finder, Bayut, etc.) and engage a RERA-registered broker. Visit properties in person or via virtual tour. Verify that the broker holds a valid DLD licence.
  3. Due Diligence and Title Verification: Before making an offer, verify the title deed via the DLD Dubai REST app or at a DLD Trustee Office. Confirm there are no encumbrances, mortgages, or disputes registered against the property. For off-plan purchases, check the developer's RERA registration and Escrow account.
  4. Make an Offer and Negotiate: Submit a written offer through your broker. Once the price and terms are agreed, both parties proceed to sign the preliminary agreement.
  5. Sign the MOU / Form F: For secondary market transactions, both buyer and seller sign the RERA Form F (Contract of Sale). A security deposit — typically 10% of the purchase price — is paid by the buyer at this stage, held in trust or by the broker pending completion.
  6. Obtain the Developer's NOC: The seller applies to the developer for a No Objection Certificate, confirming all service charges and outstanding fees are settled. This is a mandatory step before the DLD transfer can proceed.
  7. Arrange Financing (if applicable): Finalise the mortgage with your chosen bank. The bank will conduct a property valuation and issue a formal mortgage offer letter.
  8. Transfer of Ownership at the DLD Trustee Office: Both buyer and seller (or their authorised representatives) attend a DLD-approved Real Estate Services Trustee Centre. The buyer pays the purchase price (via manager's cheques), the 4% DLD transfer fee, and all applicable registration fees. The DLD registers the transfer and issues a new Title Deed in the buyer's name.
  9. Receipt of Title Deed: The new Title Deed is issued electronically by the DLD and can be accessed via the Dubai REST app. A paper copy can be requested if needed.

Required documents

The documents to prepare when buying and financing property locally.

The following documents are required to complete a property purchase in Dubai. Requirements may vary slightly depending on whether the buyer is a UAE resident or a non-resident foreigner.

  • Valid Passport: Original passport with a minimum of 6 months' validity, required for both buyer and seller (source: Aldar Real Estate / Provident Estate).
  • Emirates ID: Required if the buyer holds UAE residency.
  • Valid UAE Residence Visa: If applicable.
  • Proof of Address: A recent utility bill or bank statement confirming the buyer's residential address.
  • Bank Statements: Typically the last 3–6 months, required for mortgage applications and sometimes requested by the developer or trustee.
  • Memorandum of Understanding (MOU) / Form F: The RERA-issued Form F (Contract of Sale) is the standard preliminary agreement for secondary market transactions. It must be signed by both parties before proceeding to transfer.
  • Sales and Purchase Agreement (SPA): The formal binding contract, primarily used for off-plan purchases directly with a developer. For secondary market transactions, Form F typically fulfils this role.
  • No Objection Certificate (NOC): Issued by the developer for resale properties, confirming all service charges and outstanding fees have been settled and the property is clear for transfer.
  • Original Title Deed: The seller must provide the current title deed. Buyers can verify ownership and encumbrances via the DLD's Dubai REST app or at a DLD Trustee Office.
  • Power of Attorney (if applicable): A notarised Power of Attorney is required if a representative is acting on behalf of the buyer or seller.
  • Manager's Cheques: Payment at the DLD transfer is made by manager's cheques (certified bank cheques), not cash or personal cheques.

For off-plan purchases, the SPA must be registered with the DLD through the Oqood system, which protects the buyer's rights during the construction phase.

Legal and technical checks

Checks on title, land registry, compliance and the actual condition of the property.

Before committing to a property purchase in Dubai, buyers should conduct thorough legal and technical due diligence. The following checks are essential:

  • Title Deed Verification: Verify the seller's ownership and confirm there are no encumbrances, mortgages, or legal disputes registered against the property. This can be done instantly and free of charge via the DLD Dubai REST app (Property Enquiry function) or in person at a DLD-approved Real Estate Services Trustee Centre. For complex cases, a stamped verification certificate can be obtained within 1–2 business days (source: REDHORIZON, 2024).
  • DLD Records Check: Cross-reference all property documents with the Dubai Land Department's official records. Confirm that the title deed details (owner name, plot number, area, unit number) match the documents presented by the seller.
  • RERA and Developer Registration (off-plan): For off-plan purchases, verify that the developer is registered with RERA and that the project has an active Escrow account. The Oqood registration of the SPA protects the buyer's rights during construction. Check the developer's track record for on-time delivery.
  • No Objection Certificate (NOC): The NOC issued by the developer for resale properties confirms that all service charges, maintenance fees, and outstanding dues have been settled by the seller. Do not proceed to transfer without a valid NOC.
  • Service Charge Arrears: Request a statement of account from the developer or owners' association confirming no outstanding service charges are owed on the property.
  • Physical / Technical Inspection: Commission an independent property inspection (snagging survey) to identify any structural defects, maintenance issues, or incomplete works — particularly important for ready properties and recently handed-over off-plan units.
  • Mortgage or Liability Check: If the seller has an existing mortgage on the property, confirm the outstanding balance and the process for mortgage release (blocking) at the DLD before transfer. The seller must provide a liability letter from their bank.
  • Legal Counsel: While not mandatory, engaging a RERA-registered property lawyer to review the Form F or SPA is strongly recommended, particularly for high-value transactions, off-plan purchases, or where a Power of Attorney is involved.

Non-resident financing

Deposit, mortgage, supporting documents and constraints specific to foreign buyers.

Non-resident foreign buyers can obtain mortgage financing from UAE banks to purchase property in Dubai's designated freehold zones. While the process involves stricter conditions than for UAE residents, it is entirely achievable for buyers who meet the eligibility criteria.

  • Eligibility: Non-residents are defined as buyers without a UAE residence visa living abroad. UAE banks actively offer mortgage products to foreign investors, provided income is verifiable and meets the bank's minimum thresholds.
  • Loan-to-Value (LTV) ratio: For non-residents, the LTV ratio typically ranges between 50% and 75% of the property value, depending on the bank, the buyer's financial profile, and the property's value. This is lower than the LTV available to UAE residents, which can reach up to 80% for properties valued under AED 5 million (source: UAE Mortgage Law / lender guidelines).
  • Down payment requirements: Most non-resident applicants should budget a down payment of 25%–40% of the purchase price for ready properties, and at least 40%–50% for off-plan units (source: mortgage broker market data, 2025).
  • Key banks offering non-resident mortgages: Several major UAE banks including Emirates NBD, Mashreq, HSBC UAE, and Abu Dhabi Commercial Bank (ADCB) offer mortgage products to non-resident buyers, subject to individual eligibility assessment.
  • Required documents for mortgage application: Passport, proof of income (payslips or audited accounts for self-employed), bank statements (typically 6 months), proof of address, and details of the property to be purchased.
  • Mortgage registration fee: 0.25% of the loan amount, payable to the DLD at the time of transfer.
  • Recommendation: Obtain a mortgage pre-approval before beginning your property search. This confirms your borrowing capacity and strengthens your position when making an offer.

Investment and rental potential

Rental demand, rents, indicative yield and rules to anticipate.

Dubai's property market is widely regarded as one of the most active for buy-to-let investment, supported by strong occupancy demand from a large and growing expatriate population.

  • Gross rental yields: As of mid-2025, the average gross rental yield in Dubai stands at approximately 6.9%, with apartments averaging 7.3% and villas averaging 5.0% (source: market data, June 2025). Smaller units typically generate the highest yields: studios average 7.4%, one-bedroom apartments 6.3%, and two-bedroom apartments 5.4% (source: Property Finder).
  • High-yield areas: Jumeirah Village Circle (JVC), Business Bay, and Jumeirah Lakes Towers (JLT) consistently rank among the highest-yielding areas for apartment purchases, with gross yields ranging from 6.5% to 8.5% (source: Oliva / market data, 2024).
  • Capital appreciation: Villas in master communities such as Dubai Hills Estate have appreciated by 40–55% since launch (source: Oliva, 2024). The overall market recorded a 20% increase in average sales prices in 2024 (source: Deloitte, February 2025).
  • Short-term rental market: Dubai has a well-established short-term rental (holiday home) market regulated by the Department of Economy and Tourism (DET). Areas with strong tourist footfall — Downtown Dubai, Dubai Marina, Palm Jumeirah — are particularly suited to this strategy, though short-term rental licences must be obtained from the DET.
  • Golden Visa eligibility: Purchasing a property valued at AED 2,000,000 or more may qualify the buyer for a UAE Golden Visa (10-year residency), subject to meeting the applicable criteria set by the UAE government.
  • Key considerations: Net yield calculations should account for service charges (which vary significantly by community and building), property management fees, DET licence costs (for short-term rentals), and periodic maintenance costs.

Negotiation method

Fair-price analysis and arguments used to defend the purchase offer.

Negotiating a property purchase in Dubai follows specific market conventions that differ from many Western markets. Understanding these dynamics helps buyers secure better terms.

  • Research comparable transactions: Before making an offer, analyse recent completed sales of similar properties in the same community using DLD transaction data (available via the Dubai REST app or Property Finder's transaction history). This provides objective evidence of fair market value and strengthens your negotiating position.
  • Assess seller motivation: Review how long the property has been listed, whether the asking price has been reduced, and the seller's stated reason for selling. A seller who has already purchased another property or is relocating abroad is typically more motivated to close quickly.
  • Initial offer level: In the secondary market, it is standard practice to open negotiations below the asking price. Offering 5–10% below the asking price for resale properties is generally considered acceptable as a starting point (source: Dubai Realty Trends / Holo). In a strong seller's market, the margin for negotiation is narrower.
  • Leverage your financing readiness: Demonstrating that you have mortgage pre-approval or are a cash buyer significantly strengthens your position. Sellers and their agents prioritise buyers who can close quickly and with certainty.
  • Negotiate beyond price: In addition to the headline price, buyers can negotiate on: the size of the security deposit, the timeline to transfer, inclusion of furniture or appliances, and — for off-plan purchases — payment plan structure, post-handover payment terms, or waiver of the DLD fee by the developer.
  • Off-plan developer negotiations: When buying directly from a developer, price discounts are less common, but buyers can often negotiate on payment plan milestones, post-handover instalments, or additional unit upgrades.
  • All agreements must be formalised: Any agreed terms must be reflected in the signed RERA Form F or SPA. Verbal agreements are not enforceable under Dubai property law.

Fees and service scope

Remuneration model, included services and possible additional costs.

When purchasing property in Dubai through a RERA-registered real estate broker, the following fees and services apply:

  • Agency commission (buyer's side): The standard commission for a property sale in the secondary market is approximately 2% of the purchase price, subject to 5% VAT (source: Kotook / DLD-registered brokers). Commission rates must be clearly stated in the agency agreement and all payments must be processed through official, traceable channels. All agents involved must be registered with the DLD.
  • What the broker's service covers:
    • Property search and shortlisting based on the buyer's criteria and budget
    • Arranging and accompanying viewings
    • Market analysis and comparable sales data to support offer pricing
    • Negotiation with the seller or seller's agent on price and terms
    • Preparation and coordination of the MOU / RERA Form F
    • Coordination of the NOC process with the developer
    • Liaison with the DLD Trustee Office for the ownership transfer appointment
    • Guidance on required documents and manager's cheques
  • Legal review (optional but recommended): Engaging an independent property lawyer to review the SPA or Form F is not mandatory but is strongly advisable, particularly for off-plan purchases or complex transactions. Legal fees vary by firm and scope of work.
  • DLD fees are separate from agency commission and are paid directly to the DLD at the time of transfer (see budget-total-et-fiscalite for the full breakdown).

All RERA-registered brokers in Dubai must hold a valid DLD broker licence. Buyers can verify a broker's registration on the DLD's official portal before engaging their services.

Prepare your property purchase

Describe your project, budget and criteria. A local home finder can search for properties, organize viewings, verify information and support you during the negotiation.

Describe my project

How does it work?

1

Your home finder researches the ideal property based on your criteria.

2
They conduct property viewings, some on your behalf, others with you in person or remotely.
3
They negotiate the price and terms on your behalf. The home finder is still at 100% on the buyer's side.
4
They assist you until all documents are signed
5
It accompanies you until the signature of all documents, to avoid pitfalls.
A couple lying on a bed, embracing.

Our home finders around the world!

Remoters continues to grow!
We are recruiting new home finders, do not hesitate to apply.
World map with red markers in the Americas, Europe, Africa and Asia.I am applying

FAQ

A hand pointing at a laptop screen while the other types.

Why choose an English-speaking home finder in Dubai?

Searching for a property abroad requires time, organization, and a good understanding of local regulations, which may differ from those in France (notaries, land registry, taxation, etc.). A home finder helps simplify the process by managing the search, selecting relevant properties, organizing viewings, and reviewing legal documents.

They work closely with the buyer to define clear criteria, identify suitable opportunities, and negotiate the best possible price. They may attend property visits on the buyer’s behalf or accompany them during a stay in Istanbul.

Thanks to their local network, the home finder also facilitates the legal and logistical steps of the purchase. From the initial search to the final signature, they provide tailored support and help ensure a smooth and secure buying experience.

‍

A person in a checked shirt using a blue calculator on a wooden desk.
How much does the Remoters home finder service cost?

Remoters works with home finders around the world. Since real estate prices vary greatly depending on the location, it is difficult to apply a single pricing structure.

Each home finder sets their own fees based on the complexity of the project and the local market. You can contact them directly to learn more about their terms and evaluate the value they can bring to your purchase.

In many cases, the home finder’s fee is largely offset by negotiating a better purchase price and helping reduce legal and administrative risks.

‍

Hand holding keys with a house-shaped keychain near a door lock.
Will I have access to all the offers on the market?

There are three main types of property listings on the real estate market:

  • Agency listings
  • Private listings (from individual sellers)
  • Fast-moving listings, meaning properties that sell within days

When searching on your own, you will usually access the first two categories, provided you are familiar with the main listing platforms and able to identify outdated or misleading ads sometimes used to attract buyers. The third category often goes before you can react.

Home finders can provide access to all three types of opportunities. They screen listings before presenting them and use their network to react quickly when a relevant property comes up.

The best opportunities go fast. Being ready to make an offer as soon as a property is listed allows buyers to position themselves early. Thanks to their professional network, a home finder can help you act on these opportunities in time.

‍

Modern kitchen with a double sink, chrome tap, gas stove, green decorations and yellow lemons.
Home finder vs real estate agent

When searching for a property abroad, your need is typically a home finder🕵️

A real estate agent represents the seller through a sales mandate and aims to market properties to potential buyers.

A home finder, on the other hand, represents the buyer through a search mandate. They do not have properties to sell. Instead, they search for a specific property based on the buyer’s criteria, sourcing opportunities from both private sellers and agencies.

While the real estate agent advises and supports the seller throughout the transaction, the home finder advises and assists the buyer at every step of the purchasing process, always acting in the buyer’s best interest.

‍

A man in a suit holding a small colourful house in his hand in front of a calculator.
How do you choose the right home finder?

The right home finder is the one who helps you purchase a property that best matches your needs and criteria, at an optimized price.

Their fees should remain reasonable and create real value for your project. In many cases, the cost of the service is largely offset by stronger negotiation outcomes and better purchase conditions 🤑

When buying abroad, working with an English-speaking home finder who is well established in the local market can be particularly beneficial. This helps reduce misunderstandings and increases your chances of accessing high-quality opportunities through their local network.

Two men's hands clasped in a handshake against a neutral beige background.

Interested in becoming a home finder for Remoters in Dubai ?

You should have:

🧙 Strong experience in the local real estate market
🌐 A solid network to access a wide range of property opportunities
⚖️ In-depth knowledge of local regulations
💸 Excellent negotiation skills
🛎️ Above all, a genuine desire to support clients in their property purchase projects

If this sounds like you, we encourage you to apply — we would be happy to welcome you to our network.

Button TextButton Text